The Regime Investor· ·8 min read
Why falling US bond yields are not always bullish for shares
Why lower US long-term yields can signal disinflation, growth fear, credit stress or technical demand, with implications for Australian portfolios.
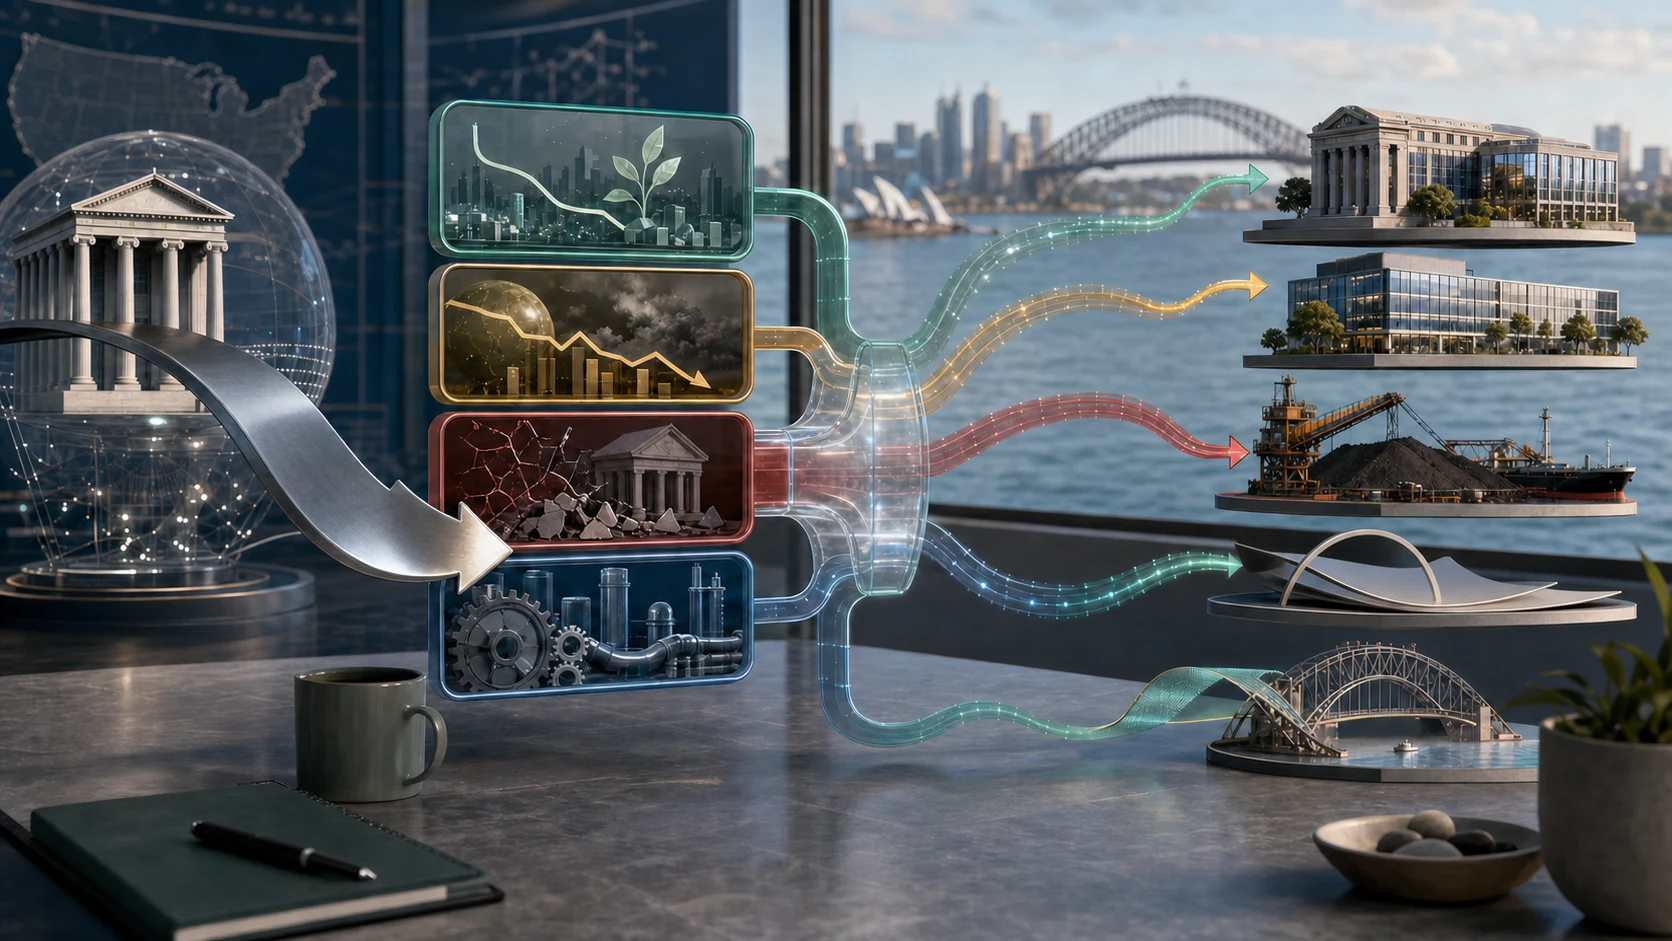
A fall in long-term US Treasury yields is often described as an automatic tailwind for shares. Lower discount rates can support valuations, especially for businesses whose expected cash flows sit far in the future. But the direction of the yield is only the first observation. The reason it moved determines whether the signal is constructive, defensive or merely temporary.
A useful reading starts by separating three ideas that are often collapsed into one number: the expected path of short-term interest rates, inflation compensation and the term premium investors require for holding a long bond. It then asks whether falling yields reflect disinflation, weaker growth, a flight to safety or a change in market plumbing. This cause-and-transmission test is part of the broader market-regime framework .
Data cut-off: 20 August 2026.
A lower yield can arrive through four different doors
Disinflation with resilient growth
This is the most supportive version. Inflation pressure eases, the expected policy path moves lower and earnings remain resilient. Lower real discount rates can then support long-duration shares without a large deterioration in expected cash flow.
Even here, valuation matters. If the market had already priced an aggressive easing cycle or unusually strong earnings, a modest fall in yields may not create much additional upside.
Growth fear
Bond yields can fall because investors expect weaker demand, lower profits and eventual policy easing. The discount rate improves, but the cash-flow outlook deteriorates at the same time.
The balance differs across sectors. A high-quality growth company may benefit from lower rates if its earnings remain intact. A cyclical company can lose more from falling revenue and margins than it gains from a lower discount rate. Banks may face a weaker credit environment or margin pressure. Commodity producers can be hit if the same growth fear lowers expected demand.
Credit or liquidity stress
During a flight to safety, investors may buy government bonds while selling shares, corporate credit and less liquid assets. Treasury yields can fall at the same time that credit spreads widen and funding conditions tighten.
That is not broad financial easing. The risk-free rate is lower, but the rate paid by a stressed borrower can still rise. Equity investors therefore need to check corporate spreads, bank funding, market liquidity and default expectations rather than reading the Treasury yield in isolation.
Technical or policy-driven demand
Buybacks, regulatory demand, pension rebalancing, dealer positioning and changes in issuance by maturity can affect specific parts of the yield curve. Those flows may improve market functioning or compress a premium without resolving the fiscal, inflation or growth forces behind the move.
A technical rally in long bonds can still matter. It can lower a reference rate and provide temporary valuation relief. It should not automatically be treated as proof that the underlying regime has changed.
What the 20 August curve said — and what it did not
US Treasury data showed a 10-year nominal yield of 4.69 per cent and a 10-year real yield of 2.35 per cent on 20 August. The simple difference was about 2.34 percentage points. At 30 years, the nominal yield was 5.23 per cent and the real yield was 2.95 per cent, leaving a difference of about 2.28 percentage points.
That difference is commonly called breakeven inflation or inflation compensation. It is useful, but it is not a pure forecast of future inflation. Federal Reserve research notes that it can contain an inflation-risk premium and the effect of different liquidity conditions in nominal Treasuries and inflation-protected securities.
The arithmetic therefore supports a question, not a verdict. If nominal yields rise while inflation compensation is comparatively contained and real yields rise, the move may reflect a higher expected real-rate path, a larger term premium or both. The observed curve alone does not identify exactly how much came from each component.
Why the term premium matters
A long-term bond exposes its holder to uncertainty for many years. The term premium is the compensation investors require for bearing that duration risk rather than repeatedly holding short-term securities. It is not directly observed; estimates depend on a model or survey assumptions.
A higher term premium can arise when investors are less willing to absorb duration, uncertainty rises or the expected supply of long bonds becomes harder to place. Fiscal deficits, Treasury issuance, foreign demand, hedging costs and competing corporate borrowing can all influence the discussion, but none proves the premium’s level on its own.
This distinction changes the equity interpretation. A yield increase caused by stronger expected growth may accompany better earnings. A similar increase caused by a larger term premium can raise discount rates without the same earnings benefit. The same yield level can therefore belong to different market regimes.
Treasury buybacks change the plumbing, not the whole borrowing requirement
The US Treasury’s August quarterly refunding statement expected up to US$38 billion of off-the-run purchases for liquidity support and up to US$25 billion in the one-month to two-year bucket for cash management during the August-to-October quarter.
On 19 August, Treasury said the amount offered per operation in the 10-to-20-year and 20-to-30-year nominal-coupon buckets would rise from US$2 billion to at least US$4 billion for operations from 9 September to 4 November. An updated schedule was to follow.
These purchases can improve liquidity in older securities and affect the long end. They do not remove the broader financing need. Treasury has said purchased securities are replaced through new issuance, so the programme is not expected to materially reduce privately held net marketable borrowing.
The durable questions are therefore about net issuance by maturity, auction demand, dealer capacity, the Treasury General Account and the behaviour of real yields and the US dollar. An election date near the operating window may motivate a hypothesis, but it does not establish political intent. The same distinction between a liquidity operation and durable monetary support also matters when assessing gold and silver as portfolio insurance .
Stablecoin reserves create another maturity-specific demand channel. Stablecoins can buy T-bills without solving America’s debt problem explains why stronger bill demand need not remove fiscal deficits or support long-duration bonds.
How the signal reaches an Australian portfolio
US long yields are global discount rates, but the transmission to Australian assets is not mechanical.
- Australian growth shares and A-REITs may receive valuation relief when global real yields fall, provided earnings and funding conditions are not deteriorating faster.
- Banks need to be read through credit quality, deposit costs, wholesale funding and the yield curve, not through one US rate.
- Resource producers can respond more to the growth and commodity-demand message behind the move than to the lower discount rate itself.
- The Australian dollar may strengthen under benign global easing but weaken during a flight to safety, changing the local return on unhedged overseas assets.
- Government and investment-grade bonds can benefit from falling yields, while longer duration also creates larger losses if the move reverses.
This is why a regime framework separates the initial market move from its cause and transmission. The same 20-basis-point fall in the US 10-year yield can be supportive in a disinflationary soft landing and defensive in a credit shock.
A five-question decision record
Before treating lower long yields as a portfolio signal, record five answers.
- Did real yields fall, or did only inflation compensation move?
- Are credit spreads and bank-funding conditions improving or worsening?
- Did earnings expectations remain stable, or are they being revised down?
- Is the move broad across maturities and markets, or concentrated in a technically affected bucket?
- What evidence would distinguish disinflation from demand destruction or a flight to safety?
No single indicator settles the answer. The value comes from checking independent transmission channels rather than counting several versions of the same price signal. The guide to testing technical indicators, backtests and probability claims explains why those are different evidence standards.
Counter-signals and conditions that would change the reading
A constructive interpretation becomes stronger when real yields ease alongside stable earnings, narrower credit spreads, improving market breadth and contained inflation. It weakens when yields fall with wider credit spreads, weaker employment, falling earnings estimates, tighter bank lending or a stronger safe-haven US dollar.
A term-premium explanation becomes more credible when long yields move independently of the expected policy path and inflation compensation, while auction demand, duration supply or market liquidity also deteriorate. It becomes less persuasive when inflation data or policy expectations clearly explain the move.
The conclusion is deliberately conditional. Falling long yields can help valuations, but they are not an automatic buy signal. First identify which door the move came through.
Update note
Revision history
This article provides general information only and does not take account of your objectives, financial situation or needs. It is not personal financial advice or a recommendation to buy, hold or sell any security.
Sources
- US Treasury, August 2026 quarterly refunding statement
- US Treasury, 19 August 2026 long-end buyback update
- US Treasury, daily nominal yield curve
- US Treasury, daily real yield curve
- Federal Reserve Board, TIPS yield curve and inflation compensation
- Federal Reserve Bank of New York, The Term Structure of Expectations and Bond Yields
More through this lens