The Regime Investor· ·12 min read
How a Fed rate hike reaches Australia: AUD, mortgages and ASX sectors
A practical guide to how a US Federal Reserve rate rise can affect the Australian dollar, RBA expectations, mortgages, banks, insurers and other ASX sectors.
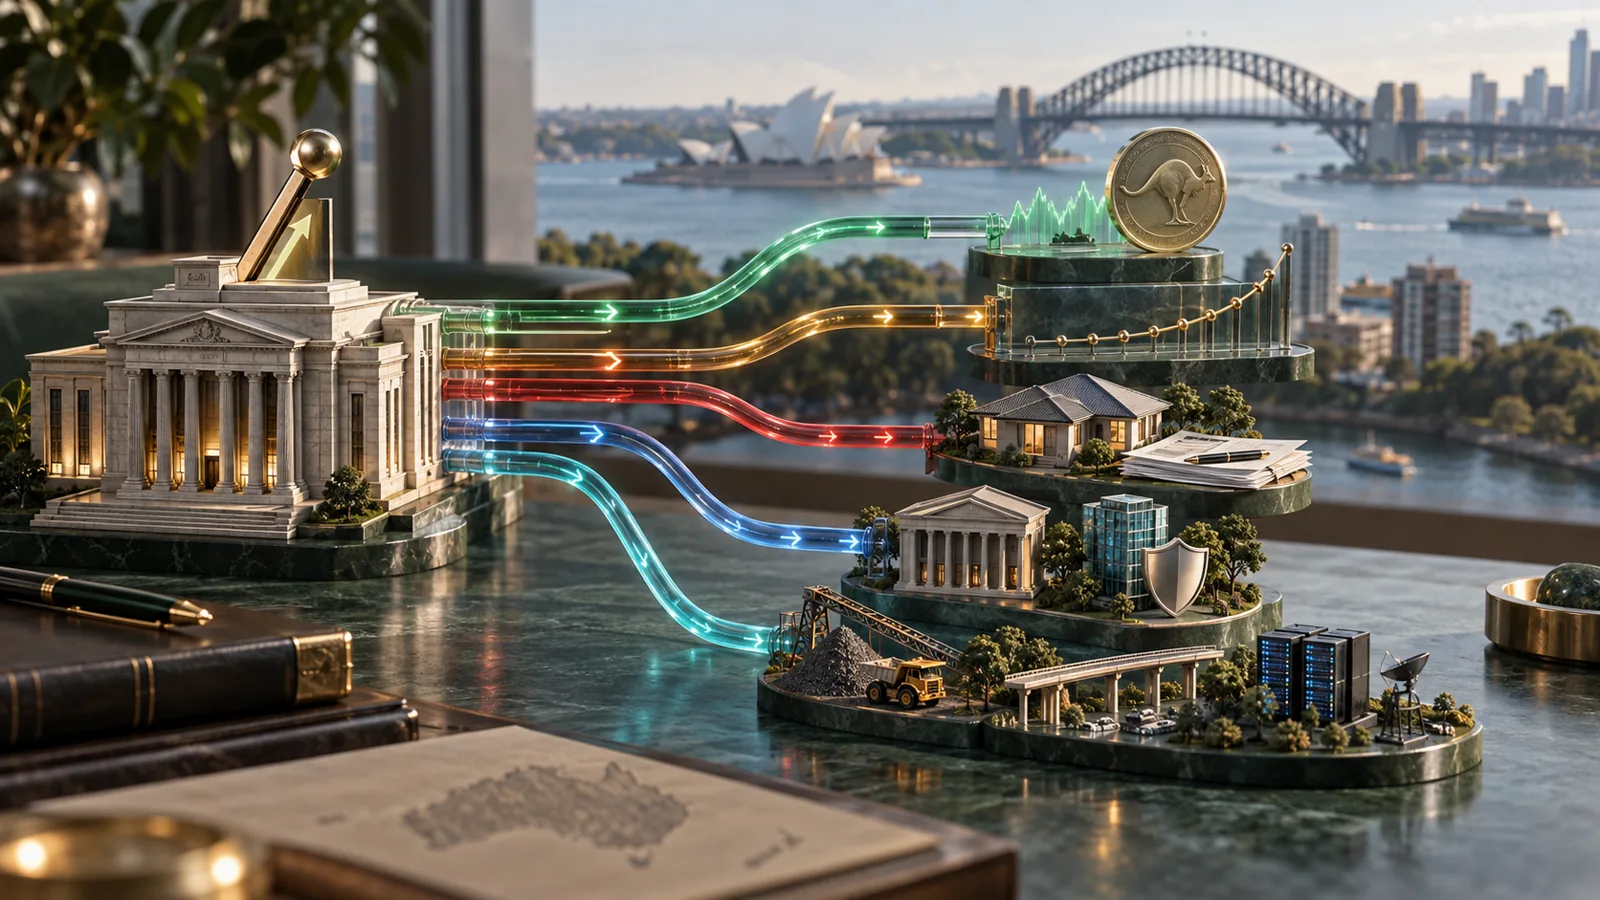
The US Federal Reserve raised its target range by 0.25 percentage points to 3.75–4.00 per cent on 16 September 2026. That does not mean the Reserve Bank of Australia must raise rates next, and it does not create a simple list of Australian “rate-hike winners”.
For an Australian household or investor, the useful question is how the US move travels through five separate channels: the Australian dollar, global bond yields, bank funding, the RBA’s inflation-and-growth trade-off, and company cash flows. Those channels can point in different directions.
The short version is:
The AUD can weaken if US yields rise relative to Australian yields, but commodity prices and global risk appetite can overwhelm that effect.
Australian mortgage rates do not change because the Fed voted. They change when the RBA cash rate, Australian market rates, bank funding costs or lender competition change.
Banks and insurers may earn more on some new assets, but deposit costs, wholesale funding, bond valuations, claims inflation and credit losses can absorb the benefit.
A lower AUD can lift the translated Australian-dollar earnings of US-dollar earners, while making imports and overseas travel more expensive.
A-REITs, infrastructure and long-duration growth shares can face a higher discount rate and refinancing cost even if their current revenue does not change.
The point is not to predict every market move from one central-bank decision. It is to identify which Australian transmission channel is actually moving and what would invalidate the conclusion.
Data cut-off: 17 September 2026. This captures the Fed decision and the Australian evidence available at that time; it does not treat the post-decision Australian market response as settled.
Holdings disclosure: The author or operator may hold Australian or global shares, bonds, funds, cash or other broad exposures discussed in this article. Commercial disclosure: This article was not commissioned or sponsored by a bank, insurer, broker, fund manager or product issuer and contains no affiliate or broker-referral links. Automatically selected display advertising, if enabled, does not determine the editorial view.
Australia is not importing the Fed’s policy rate
The Fed sets an overnight policy range for the United States. The RBA sets Australia’s cash rate according to Australian inflation, employment, demand and financial conditions. The two central banks can move in the same direction, in opposite directions or at different speeds.
At its August meeting, the RBA left the cash rate at 4.35 per cent after three increases earlier in 2026. Its August assessment described Australian financial conditions as somewhat restrictive and noted that the earlier increases had not yet had their full effect. That assessment already incorporated a higher expected US policy-rate path and rising US yields. The incremental Australian effect of the September vote therefore depends on whether the decision, guidance and later market pricing differ from what investors had already expected; the vote does not replace the RBA’s domestic test.
The immediate Australian question is therefore not “Will the RBA copy the Fed?” It is whether the US move changes the AUD, imported inflation, global yields, credit conditions or the growth outlook enough to alter the RBA’s own balance of risks.
The first channel is the Australian dollar
Interest-rate differentials are one influence on exchange rates. If expected returns on US-dollar assets rise relative to comparable Australian-dollar assets, demand can shift towards the US dollar and put downward pressure on the AUD. The RBA’s August financial-conditions review attributed part of the Australian dollar’s recent depreciation to a narrowing in Australia’s yield differential with other advanced economies, particularly as US yields rose.
That relationship is not a formula. The AUD also responds to iron ore and other commodity prices, China’s outlook, global risk appetite and the reason US rates are rising.
A weaker AUD produces mixed Australian effects:
Imports, overseas travel and US-dollar costs become more expensive in Australian dollars.
Exporters and multinational businesses can receive more Australian dollars for unchanged foreign-currency revenue, although hedges and foreign costs can delay or reduce the benefit.
Unhedged global shares rise in Australian-dollar terms when the AUD falls, all else equal; the reverse applies when the AUD strengthens.
More expensive imports can add to inflation pressure, but the size and timing of pass-through vary by product, margins and demand.
So “Fed up, AUD down” is a hypothesis to test against the currency, commodity prices and risk sentiment—not a position to assume.
The second channel is global bond yields, not Australian mortgages directly
US Treasury yields influence global discount rates and the price at which governments and companies can borrow. Australian government-bond yields can move with them, but domestic policy expectations and local inflation can create a large gap.
The RBA observed this divergence before the latest Fed decision: US government-bond yields had risen since its May Statement, driven partly by higher real yields and tighter policy expectations, while Australian yields were slightly lower alongside a reduced expected path for the local cash rate.
This distinction matters for households. A Fed increase does not mechanically add 0.25 percentage points to an Australian mortgage. The relevant path is:
US policy and yields → global and Australian wholesale markets → bank funding and hedging costs → lender pricing,
combined with the separate path:
Australian inflation and demand → RBA cash rate → Australian deposit and lending rates.
Competition can interrupt both paths. A lender may absorb part of a cost increase to defend market share, while another may reprice a product because its own deposits, wholesale debt, hedges and credit risks differ.
The same reason-first rule explains why falling US bond yields are not automatically bullish for Australian shares : the cause and transmission path matter more than the headline direction.
The RBA faces a two-sided test
A Fed increase can make the RBA’s job harder through a weaker AUD and more expensive imported goods. It can also tighten global financial conditions, weaken demand and reduce commodity prices, which would pull in the opposite direction.
This creates three plausible Australian cases.
US resilience, limited Australian spillover
US activity remains firm, the AUD moves only modestly and Australian inflation continues to ease. The RBA can keep judging local data rather than following the Fed. Australian mortgage rates need not move simply because the US policy range rose.
Currency-led inflation pressure
The US–Australia yield differential shifts further towards the United States, the AUD weakens and import-price pressure becomes broader. If domestic inflation is already persistent, the RBA may have less room to ease or may need to maintain restrictive settings for longer.
Global tightening becomes a growth shock
Higher US yields weaken global demand, commodity prices and risk assets. The AUD can still be weak, but the hit to Australian growth and employment may eventually dominate the inflation effect. In that case, a Fed hike can increase the probability of later Australian easing rather than another local increase.
These are scenarios, not forecasts. The correct one depends on the transmission evidence that follows the decision.
Banks: higher rates help only after funding and credit costs
Australian banks earn a spread between asset yields and the cost of deposits, wholesale debt and hedging. Higher market rates can lift returns on variable loans and new securities, but they also reprice deposits and debt.
The RBA estimated in August that major-bank funding costs had risen by 18 basis points since its May Statement as the higher Australian cash rate flowed through to deposits and wholesale debt. It also reported that variable mortgage rates had risen by nearly 75 basis points between January and June, although some lenders later cut selected advertised rates as competition remained strong.
That is why a US rate rise is not automatically bullish for ASX banks. Check the whole earnings bridge:
Did loan and liquid-asset yields rise?
Did deposit and wholesale-funding costs rise faster?
Did the bank have to discount new mortgages to protect volume?
Are arrears, hardship, provisions and realised credit losses deteriorating?
Did hedges delay or reverse the apparent benefit?
A bank can report higher asset yields and a lower net interest margin at the same time. It can also maintain margin briefly while future credit losses are building. The relevant result is the net effect, not the direction of one rate.
For the bank-specific version of this test, see how mortgage competition changes Australian bank earnings .
Insurers: reinvestment yield is only half the story
Higher bond yields can allow insurers to invest new premiums and maturing assets at better yields. That can improve investment income over time, particularly when liabilities are long-dated and assets can be held through market volatility.
The offsetting Australian questions are different from those for banks:
How quickly does the investment portfolio mature and reprice?
Are existing bond holdings carrying unrealised losses?
Do higher rates or cost-of-living pressure increase lapses?
Are claims costs rising with wages, repairs, construction or medical expenses?
Does the insurer hold enough capital and liquidity to avoid selling assets at a poor time?
For general insurers, claims inflation and catastrophe exposure may matter more than a modest change in investment yield. For life insurers, asset–liability matching and lapse behaviour can determine whether the higher reinvestment rate becomes durable profit.
These are questions to test against each insurer’s financial statements rather than a claim that sector profit moves uniformly. Accounting classification, the remeasurement of insurance liabilities and the degree of asset–liability duration matching can offset or defer an apparent gain or loss on the asset portfolio.
A sector map for an Australian portfolio
Banks
Possible benefit: Higher yields on some loans and liquid assets
Main offset: Deposit competition, wholesale funding, mortgage discounting and credit losses
What to verify: Net interest margin, deposit mix, funding cost, arrears and provisions
Insurers
Possible benefit: Higher reinvestment yields
Main offset: Asset and liability remeasurement, accounting mismatch, lapses, claims inflation and capital strain
What to verify: Investment yield, asset–liability duration matching, accounting classification, claims ratio, lapse rate and capital
US-dollar earners and exporters
Possible benefit: More AUD for foreign-currency revenue if the AUD weakens
Main offset: Foreign costs, hedging and weaker global demand
What to verify: Revenue currency, cost currency, hedge book and volume outlook
A-REITs and infrastructure
Possible benefit: Contracted revenue with genuine inflation indexation or escalation can provide some protection
Main offset: Higher discount rates and refinancing costs; long fixed nominal cash flows can increase duration sensitivity
What to verify: Indexation terms, debt maturity, fixed-rate share, hedges, covenant headroom and refinancing schedule
Long-duration growth shares
Possible benefit: None from the rate rise itself; strong earnings can offset valuation pressure
Main offset: Higher discount rate and tighter funding
What to verify: Free cash flow, capital needs, earnings revisions and valuation
Resource producers
Possible benefit: A lower AUD can support local-currency revenue
Main offset: Commodity-price falls and weaker global demand
What to verify: Commodity price, realised AUD price, costs, volumes and hedges
Unhedged global assets in super
Possible benefit: Foreign holdings translate into more AUD if the AUD falls
Main offset: Underlying asset losses or later AUD rebound
What to verify: Currency hedge ratio, asset allocation and underlying earnings
This is a verification map, not a list of recommendations or a forecast of uniform sector outcomes. Two companies in the same sector can have opposite outcomes because their contracts, accounting treatment, debt maturities, currency hedges, deposit franchises or cost bases differ.
Six indicators to watch after the decision
AUD/USD and the trade-weighted index. A sustained move matters more than a brief announcement reaction.
Australian–US two-year and ten-year yield differentials. The short end carries policy expectations; the long end also includes inflation, growth and term-premium effects.
Australian bank funding measures. Deposit rates, bank bill swap rates and bank-bond spreads show whether the global repricing is reaching local funding.
Mortgage and deposit repricing. Advertised rates are clues; average rates actually paid reveal the aggregate pass-through with a lag.
Credit quality. Mortgage arrears, hardship, business failures and provisions test whether higher income yields are being lost to bad debts.
Earnings revisions and currency exposure. ASX sector performance is more credible when analysts’ cash-flow estimates move for an identifiable reason, not merely because a theme label is popular.
Avoid counting correlated indicators as independent confirmation. A stronger US dollar, weaker AUD and a wider US–Australia yield differential may all be different views of the same currency channel. The thesis is stronger when funding, company earnings and credit quality confirm it separately.
What would change the assessment
The currency-led inflation case weakens if the AUD stabilises, commodity prices recover and import-price pass-through remains narrow. It strengthens if the currency decline persists and businesses report broader cost increases.
The bank-benefit case weakens if deposit costs, wholesale funding or credit losses rise faster than asset yields. It strengthens only when net interest margin, asset quality and capital remain sound together.
The “higher rates hurt long-duration assets” case weakens if yields rise because growth and company earnings improve enough to offset the higher discount rate. It strengthens when real yields rise while earnings forecasts fall and refinancing needs approach.
Most importantly, the Australian policy conclusion changes if domestic inflation, wages, employment or demand diverge from the US story. The Fed decision is an external input; only a decision or guidance surprise that changes market pricing creates a new financial shock. The RBA decision remains Australian.
Bottom line
A Fed rate hike reaches Australia through markets before it reaches most household contracts. Watch the AUD and yield differentials first, then bank funding and the RBA’s domestic inflation-and-growth test. Only after those links move should an investor infer an effect on mortgages or ASX earnings.
There is no universal Australian rate-hike winner. Banks, insurers, exporters, A-REITs, resource companies and unhedged global assets each have a potential benefit and a separate failure condition. The useful framework is:
US policy decision or repricing → Australian transmission channel → company or household cash flow → offsetting cost → evidence that would change the view.
That sequence turns a US headline into an Australian decision record without pretending that the RBA, the AUD or the ASX must follow a fixed script.
This article provides general information only and does not take account of your objectives, financial situation or needs. It is not personal financial advice or a recommendation to buy, hold or sell any security.
Sources
Federal Reserve — FOMC statement , 16 September 2026
Reserve Bank of Australia — Financial Conditions, August 2026
Reserve Bank of Australia — Implications of US policy settings for financial markets
Reserve Bank of Australia — The transmission of monetary policy
Reserve Bank of Australia — Banks’ funding costs and lending rates
More through this lens