The Regime Investor· ·5 min read
How to test a physical silver shortage: seven indicators
Test a physical silver shortage through exchange stocks, open interest, futures curves, lease rates, fund holdings, regional premiums and real yields.
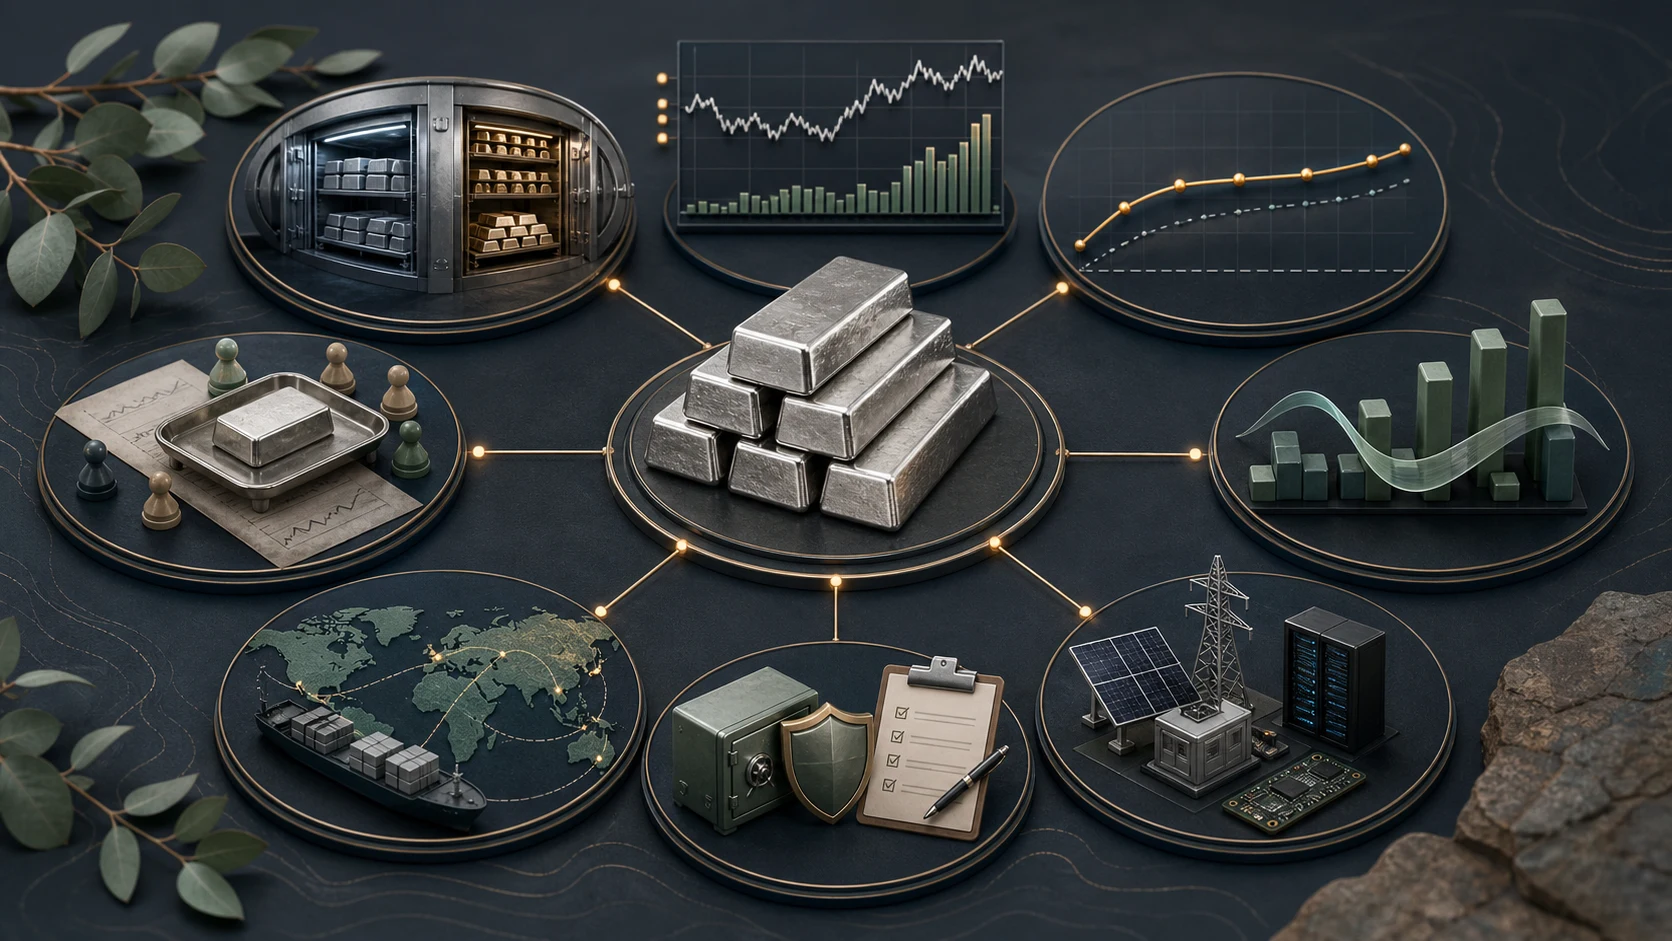
When silver rises sharply, a familiar claim follows: futures contracts exceed exchange stocks, so physical metal must soon run out. The numbers are dramatic, but that comparison alone cannot establish a shortage or default.
Many futures positions are closed or rolled before delivery. Metal in an approved vault can also move between registered and eligible categories. Testing whether the physical market is genuinely tight requires indicators that measure different transmission paths.
Evidence cut-off: 23 August 2026.
1. Separate registered and eligible stocks
Under CME’s precious-metals delivery guide, registered metal has a warrant issued and can be used for futures delivery. Eligible metal is in an approved depository and meets contract specifications, but no delivery warrant has been issued.
A fall in registered stock therefore does not necessarily mean metal has left the vault. An owner can cancel a warrant and move stock from registered to eligible. Compare registered, eligible and total stocks with vault receipts and withdrawals on the same date.
2. Open interest matters more near expiry
Open interest counts futures contracts that have not yet been closed. Multiplying contracts by ounces produces a large number, and claims of imminent default often begin when that number exceeds registered stocks.
Not every holder intends to take metal. Positions can be offset or rolled before expiry. The useful questions are how open interest changes into the notice period, whether delivery notices rise and whether warrants actually move.
3. Read the futures curve after carrying costs
Contango means a later contract is priced above a nearby contract. Backwardation means the nearby contract is more expensive and can indicate a premium for immediately available metal.
The curve still has to be compared with financing, storage, insurance and other carrying costs. A market can look superficially in contango while remaining tight relative to fair carry. One brief backwardation is not proof of a structural shortage.
4. Check lease and swap rates with their terms
A sharp rise in the cost of borrowing silver or exchanging spot and forward exposure can indicate that metal is difficult to obtain in a particular location or tenor. The Silver Institute described elevated lease rates and regional liquidity tightness in the London market during 2025.
Lease-rate series differ by source, maturity, collateral and market liquidity. A single unattributed negative or positive rate should not be converted into a risk-free arbitrage or a claim of global exhaustion.
5. Pair fund flows with physical holdings
Inflows into silver exchange-traded products can require additional metal and make investment demand compete with industrial use. Redemptions can work in the other direction by releasing holdings back to the market.
Price alone is insufficient. Compare holdings, creations and redemptions, lending arrangements, custody location and discounts or premiums to net asset value. Avoid double-counting the same metal across funds or custodial chains.
6. Connect regional premiums with physical movement
Shanghai or Indian premiums, imports, exchange stocks and wholesale withdrawals can reveal physical demand. A high regional price alone does not prove that all Western silver is moving east.
Currency, tax, purity, transport, bonded-warehouse rules, re-exports and reporting lags matter. The interpretation becomes stronger when adjusted premiums, imports and declining inventory persist together and the shipment route can be verified.
7. Overlay real yields and industrial demand
Silver pays no interest, so higher real yields can increase its opportunity cost. Lower real yields and a weaker US dollar can support investment demand, although neither relationship is mechanical.
Silver is also used in solar panels, power grids, vehicles, electronics and data centres. The Silver Institute’s 2026 outlook projected a sixth consecutive annual market deficit while expecting industrial demand to decline as photovoltaic manufacturers reduced or substituted silver use. A deficit and weaker demand can exist at the same time.
The indicators answer different questions
Inventory, open interest and the futures curve measure exchange-delivery pressure. Lease rates measure access in the wholesale market. Fund flows track investor demand. Regional premiums help trace physical movement. Real yields and industrial activity describe the wider price environment.
These are more useful than several indicators derived from the same price series. A shortage case strengthens when independent transmission paths tighten together. When they conflict, the evidence supports patience rather than a forced conclusion.
Counter-signals and conditions that would change the view
The shortage case weakens if registered and total stocks recover, the curve returns to normal carrying-cost relationships, lease rates ease, fund holdings decline, regional premiums narrow and real yields rise.
It strengthens if delivery demand remains high into notice periods, registered and total stocks fall together, backwardation persists after carrying costs, fund inflows continue and Asian premiums broaden alongside verified imports.
This checklist is not a target-price formula. Australian investors still need to consider silver’s volatility, currency exposure, spreads, custody, tax and the tracking structure of the chosen vehicle.
The broader guide to gold and silver as portfolio insurance compares the metals’ roles and Australian holding structures. The guide to technical indicators and evidence independence explains why several versions of one price signal should not be counted as separate proof.
This article provides general information only and does not replace personal investment, legal or tax advice.
Sources
More through this lens